A burst pipe, falling tree, or kitchen fire can leave you deciding what to do before you even know what the insurance company needs. The best approach is to separate safety from paperwork: protect people, capture evidence, prevent further damage, and then report the loss. This step-by-step guide explains how to file a homeowners insurance claim without losing track of deadlines, receipts, or important questions.
Step 1: Handle safety before paperwork
Leave the property if there is danger from fire, structural damage, exposed wiring, or contaminated water. Call emergency services when needed. Do not enter standing water near electrical equipment or climb onto a damaged roof for photographs.
Once the danger is controlled, take reasonable action to avoid additional damage, such as calling a plumber to stop a leak. You can document the scene when it is safe; no photograph is worth an injury.
Step 2: Check your coverage and deductible
Find your policy number, coverage limits, deductible, and any special deductibles for wind or hurricanes. Read the sections describing the cause of the damage. A standard homeowners policy generally excludes flooding from rising outside water, which usually requires separate flood coverage. Long-term wear and neglected maintenance also may not be covered.
Compare a rough repair estimate with your deductible if the damage is minor. Filing a claim can affect future insurance costs or renewal decisions, although outcomes vary. For serious damage, do not delay reporting while waiting for perfect estimates. Deadlines depend on your policy and state.
For more background before calculating your potential payment, review the differences between homeowners insurance deductibles and coverage limits.
Step 3: Record what was damaged
Take wide photographs of each affected area followed by close-ups. Make a short timeline: when the event occurred, when you discovered damage, and what happened next. Photograph damaged furniture and appliances before moving them, if safe.
Prepare a room-by-room inventory listing each item’s description, approximate age, and estimated replacement cost. Collect receipts, purchase emails, warranties, and older photographs. One of the most effective claim documentation tips is to keep the original files in one folder and submit copies through the insurer’s approved channel.
Consider an upstairs bathroom supply line that bursts. Photograph the pipe, wet bathroom flooring, ceiling stains downstairs, and damaged furniture. Save the plumber’s report showing when water was shut off. Together, these details explain the sequence of the loss more clearly than an unsupported repair total.
Step 4: Prevent additional damage
Arrange temporary measures such as a properly installed tarp, boarded window, or emergency water extraction. Keep invoices and before-and-after photographs. Reasonable mitigation expenses may be covered when related to an insured loss, but ask your insurer about its requirements.
Keep damaged materials for an insurance adjuster visit when practical and safe. If mold, contamination, or another hazard makes disposal necessary, photograph the materials and record what was removed. Avoid authorizing extensive permanent repairs before the insurer has had an opportunity to inspect, unless safety requires immediate work.
Step 5: Contact the insurer promptly
Call the number on your policy or use the insurer’s claims portal. Provide your policy number, address, contact details, date of loss, and a factual description. You do not need to know the final repair cost yet.
Ask for a claim number, document-upload instructions, applicable deadlines, and the next inspection step. Record the representative’s name and date of contact. A simple claim log with dates, promises, and follow-up questions prevents small misunderstandings from turning into delays.
Step 6: Prepare for the insurance adjuster visit
The insurer may send a staff or independent adjuster to assess the damage. Have your photo folder, inventory, emergency invoices, and available contractor estimates ready. Walk through the affected rooms and point out damage that may not be immediately visible.
Ask when the written estimate will arrive and how to report additional damage discovered later. An estimate can change when contractors uncover concealed problems. If your contractor disagrees with the scope, request a written explanation and supporting measurements rather than simply insisting on a higher amount.
Step 7: Complete a proof of loss form if required
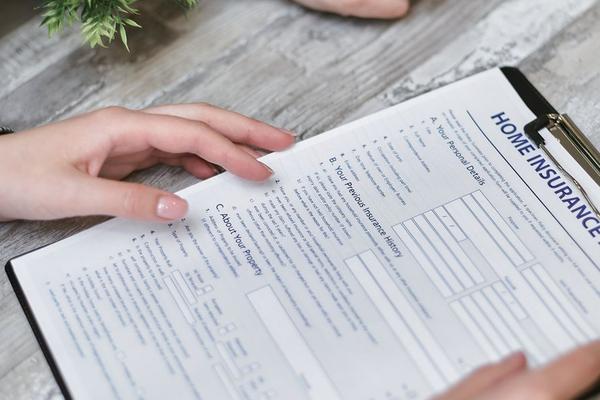
Your insurer may request a signed proof of loss form stating the claimed amount and supporting information. Ask which form applies and the exact submission deadline. There is no universal proof-of-loss deadline for every homeowners policy.
Check quantities and amounts before signing, and attach receipts or estimates requested by the insurer. Flood insurance operates under different rules: the National Flood Insurance Program generally requires a sworn proof of loss within 60 days, unless a waiver or extension applies. Do not assume a flood-policy deadline governs an ordinary homeowners claim.
Step 8: Examine the settlement estimate
Compare each line of the insurer’s estimate with the contractor’s scope. Look for missing rooms, labor, cleanup, or damaged items. If something is omitted, request a correction supported by photographs, measurements, or a detailed bid.
Ask whether the policy pays actual cash value or replacement cost. An initial payment can reflect depreciation, with eligible recoverable depreciation potentially paid after repair or replacement documents are provided. Deductibles, limits, and exclusions also affect the final amount. For a deeper explanation, review replacement cost versus actual cash value coverage.
If your home is uninhabitable because of covered damage, ask about additional living expenses. Save hotel, rental, and eligible extra-expense receipts. Building-damage payments may also require your mortgage lender’s endorsement.
Step 9: Respond to disagreements in writing
If you believe damage was overlooked, submit photographs and a contractor’s itemized explanation. Request a supplemental review. Keep your questions specific: identify the affected area, the disputed cost, and the evidence supporting it.
For a denial, ask for the written reason and the policy language relied upon. Your policy may provide appraisal or other dispute options. Your state insurance department can explain consumer complaint procedures, although it cannot guarantee a particular settlement.
Step 10: Save the complete claim file
Keep emails, claim numbers, estimates, payment statements, proof-of-loss submissions, receipts, and photographs together. Document completed repairs too. These records may matter if new related damage is found or a future claim raises questions about earlier work.
Frequently Asked Questions
How soon should I file a homeowners insurance claim?
Notify the insurer as soon as practical. Ask for any reporting, inspection, or paperwork deadlines in writing because requirements vary by policy and state.
Can I make repairs before the adjuster arrives?
Make necessary emergency repairs to reduce further damage. Photograph conditions when safe, keep receipts, and coordinate major permanent repairs with the insurer.
What if I have no receipts for damaged belongings?
Use order histories, bank statements, photographs, manuals, or other reliable records. Be clear about estimates rather than inventing purchase details.
Will a homeowners claim raise my premiums?
It can, depending on claims history, the loss, insurer practices, and state rules. Ask your insurer or agent how claim history is considered.
Move from damage to a documented recovery
The homeowners claim process works best when each decision leaves a clear record. Prioritize safety, report promptly, keep the evidence organized, and review the insurer’s estimate carefully. Those habits help you ask better questions and move toward repairs with fewer avoidable surprises.